
Blog: Pricing & AI—Retail Analytics and Strategies
The newspaper of the pricing

Specialty retailers account for 30% of organic sales but drive most of the growth, and even regular organic shoppers do most of their shopping at supermarkets. The best benchmark is the type of store the customer visits within the same week.
Two organic prices recorded in two different retail channels rarely refer to the same product: they must be adjusted to account for differences in size, brand, label, and origin. This is a matching process that does not cover markets and direct sales without on-site data collection.

Price remains the primary barrier to organic products, but consumer perception is shaped by a few key products and the cumulative price difference across the shopping basket. The actual price difference varies widely: in June 2026, it ranged from +8% for bananas to +114% for apricots.
A price reduction on organic products only pays off when customers have a point of reference for comparison, when their price sensitivity is moderate, and when there is sufficient margin to support it. It must also be noticeable and sustained: if spread out across the entire aisle, it costs money without making a difference.

The organic market returned to growth in 2025, but price remains the top obstacle cited. Customers do not judge the organic section based on an average: they focus on the price difference among the few dozen products they compare and apply that conclusion across the board.
Organic pricing is therefore determined by product category—with a focus on these specific items and a higher margin elsewhere—and by catchment area rather than through a single national pricing schedule. Local variations are still limited by central guidelines.

Most pricing projects begin by importing files that the company already exports, not through an API integration. There are three levels (files, scheduled connector, real-time API), and the lack of a connector is never a valid reason to postpone the project.
The required freshness of data depends on the decision-making cycle: for prices updated weekly, a weekly import is equivalent to an API. The real risk of starting with files is the silent drift in formats, which is why controlled imports are necessary.

The average basket size and purchase frequency help refine a price tier, but they are not a prerequisite. The selling price, purchase price, and volume sold per SKU are sufficient to establish a pricing grid, and the first inconsistencies in the tiers become apparent in the catalog, even without any receipt data.
When data is limited, we track a product family’s ranking rather than the price of each SKU; we look at its price position weighted by volume, and we differentiate rankings by channel. The grid is then expanded as more data becomes available, without having to start from scratch.

Before switching to a new pricing tool, it is important to determine why the first one was not adopted: most of the reasons are related to project management and will persist as the company transitions to the new tool. Usage data from the old tool is the best source of information for this analysis.
Re-enter the data and review the rules: copying them all at once carries over the workarounds from the first project. Running both tools in parallel through a pricing cycle is better than a lengthy set of specifications.

A price discrepancy between a store, a curbside pickup service, a website, and a marketplace is not a problem in and of itself: price consistency does not require uniformity. It becomes a problem when no one can explain why it exists or who decided on it.
For a multi-format retailer, the right architecture is a common policy implemented through targeted frameworks, where the cost or use of the channel justifies it. In the food retail sector, price parity between in-store and curbside pickup remains the norm and serves as a line of defense for the brand’s price image.
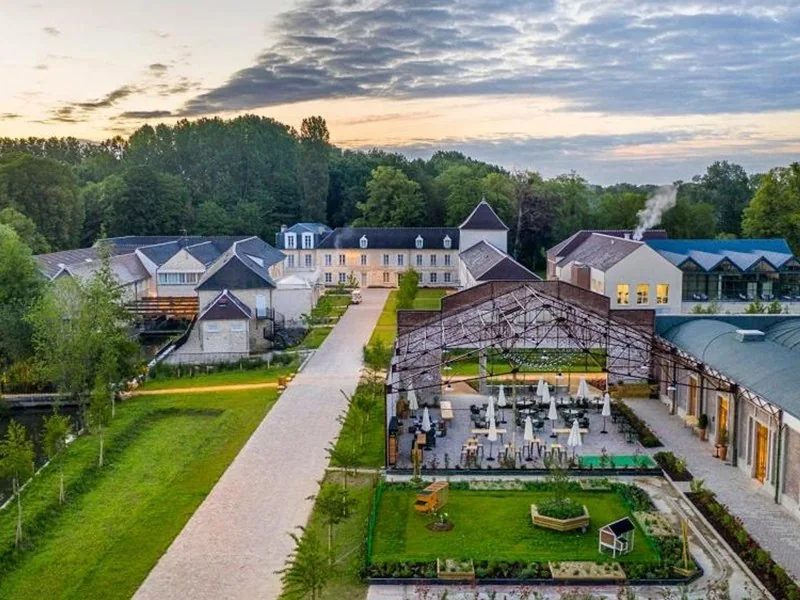
Booper is participating for the second time in Spot, the retail industry’s back-to-school seminar, in Chantilly on October 1 and 2, 2026. We will be hosting a panel discussion titled “AI & Domain Expertise: Retail’s New Winning Combination,” featuring Ines Amor, who holds a Ph.D. in AI and data science, and Hugues Lafitte, who has over 10 years of experience in retail pricing.

Booper will be participating in NRF 2026: Retail's Big Show Europe, at Paris Expo Porte de Versailles, from September 15 to 17. Visit the team at booth I027 (Hall 6) to discuss AI-driven pricing and business rules, balancing margin, price image, and purchasing power.
In France, a suggested retail price (SRP) is never binding on the retailer: the retailer remains free to sell at a higher or lower price, with the only lower limit being the sale at a loss. What the law prohibits is imposing a minimum resale price, either directly or indirectly, and a retailer who accepts such a system may also be subject to penalties.
The MSRP reflects the margin the manufacturer intends for its entire distribution network, not the role of the product as a benchmark on your shelf. Adjusting it may be justified for products that customers compare; otherwise, it’s a margin decision to be made category by category, rather than a legacy setting.
A price reduction applies to all existing sales, not just new sales. The additional volume must offset this discount granted to everyone, and the threshold to be reached rises even faster when the “ Gross margin ” is low.
A price reduction is structurally more expensive than a price increase: at a 25% Gross margin, a 10% price reduction requires an elasticity of 6.7, whereas a 10% price increase requires only 2.9. Most price reductions are therefore justified by pricing strategy or inventory considerations and should be treated as an investment.
In the retail sector, a product's profitability isn't determined solely by its selling price. Part of it is determined on the shelf (the front-end margin), and another part is negotiated with the supplier, off the sales receipt (the back-end margin).
Far from disappearing, the back-end margin is shifting toward services and international operations. Managing one without the other often leads to underestimating—or overestimating—the actual profitability of a product.
The margin, the Gross margin , and the Markup do not measure the same thing, and confusing them distorts all the resulting pricing decisions.
Once the formulas are in place, the challenge becomes operational: tracking a margin that fluctuates weekly, item by item, and assigning each category its own target rather than a single rate recalculated once a quarter.

When sales stagnate, price is the first thing to take the blame because it’s the simplest explanation. The problem often lies elsewhere: a value proposition that hasn’t been clearly communicated to the customer, or a competitive comparison skewed by outdated data or poor product matching.
Prices change quickly: in France, 5.5% of online food prices change every week, according to the Banque de France. Checking the comparison before adjusting the price prevents you from sacrificing profit margin due to a discrepancy that exists only in the database.

Pricing governance determines who proposes, approves, and resolves disputes depending on the issue at hand. A decision made by a single department optimizes only one aspect, and the problem stems primarily from the lack of information flow between procurement, category management, and pricing.
We need to share the perspective, not the decision: each price has an owner, but everyone works with the same costs and the same simulations. Most prices follow rules that have been approved once; only decisions that commit the brand are escalated to the committee and management.