
Break-even point
On this page
Do you know how much more you can sell after a price reduction?
Let's plan an exchangeDiscover our price diagnosticThe break-even point is the sales volume at which a business covers all of its costs—both fixed and variable—without making a profit or incurring a loss. Below this point, the business operates at a loss; above it, each additional unit contributes directly to the margin. Formula: fixed costs ÷ unit contribution margin.
The Essentials
- The break-even point reflects a pricing decision based on the minimum volume to be sold—something that no single Markup can indicate on its own.
- We calculate it once, then lower the price without checking how much additional volume that price reduction requires.
- Before signing, he asks: Will this price cut, promotion, or product launch remain profitable at the expected volume?
Le point mort expliqué en 1 minute
Expliqué par Edouard Calliati, CMO-CRO de Booper · vidéo publiée le 8 novembre 2026
Lire la transcription de la vidéo
Vous baissez un prix pour vendre plus. Bonne idée ?
Peut-être... Mais combien de produits en plus faudra-t-il vendre, juste pour ne rien perdre ?
La réponse, c'est le point mort : le volume de ventes qui couvre tous les coûts. Ni perte, ni bénéfice.
Le calcul : coûts fixes, divisés par la marge contributive unitaire. Ce que rapporte chaque produit, une fois payés ses coûts variables.
Exemple : une gamme de cosmétiques lancée avec deux cent cinquante mille euros de coûts fixes. Vendu vingt-huit euros, chaque produit en coûte huit : vingt euros de marge.
Point mort : douze mille cinq cents unités.
Et à vingt-quatre euros ? La marge tombe à seize euros, et le point mort grimpe à plus de quinze mille six cents unités.
Quatre euros de remise, plus de trois mille ventes à trouver !
Le piège ? Un seul point mort pour tous les canaux.
En ligne, livraison et retours coûtent plus cher : un produit rentable en magasin peut perdre de l'argent sur le site !
Avec Booper, l'impact d'une baisse de prix sur votre seuil de rentabilité se simule avant la décision, référence par référence.
Le point mort : les ventes à atteindre avant le premier euro gagné. À retenir !
The break-even point explained in 1 minute
Explained by Edouard Calliati, CMO-CRO at Booper · video published on 11 November 2026
Read the video transcript
Picture this: you cut a price to sell more. Good idea?
Maybe... But how many extra units must you sell, just to break even?
The answer is your break-even point: the sales volume that covers all your costs. No loss, no profit.
To calculate it, divide fixed costs by the unit contribution margin: what each unit earns after its variable costs.
Take a cosmetics range with two hundred and fifty thousand euros of fixed costs. Sold at twenty-eight euros, costing eight: twenty euros per unit.
Break-even: twelve thousand five hundred units.
At twenty-four euros? Margin drops to sixteen, and break-even climbs past fifteen thousand six hundred.
Four euros off: over three thousand extra sales!
Watch out for a single break-even point! Online, delivery and returns cost more: a product that pays its way in store can lose money online.
With Booper, the impact of a price cut on your break-even point is simulated before you decide, product by product.
Break-even point: the sales you need before earning your first euro. Key takeaway!
In 6 Questions
The break-even volume that covers both fixed and variable costs.
Pricing teams, management accounting teams, and product managers.
Before a launch, a price reduction, or a promotion.
By product, category, or project.
Determining whether a pricing decision remains profitable.
Fixed costs ÷ unit contribution margin.
Why the Break-Even Point Informs Pricing Decisions
Because it tells you how much you need to sell so that a price, a promotion, or a product launch doesn't result in a loss.
- Determine the minimum volume below which a product SKU reduces value within the product mix.
- Assessing pricing flexibility: A product that is well above its break-even point can withstand more aggressive promotions.
- Setting a launch target: the minimum volume to be achieved within the first six months.
Real-world example: 12,500 units to break even on a launch
With €250,000 in fixed costs and a contribution margin of €20 per unit, the break-even point is 12,500 units.
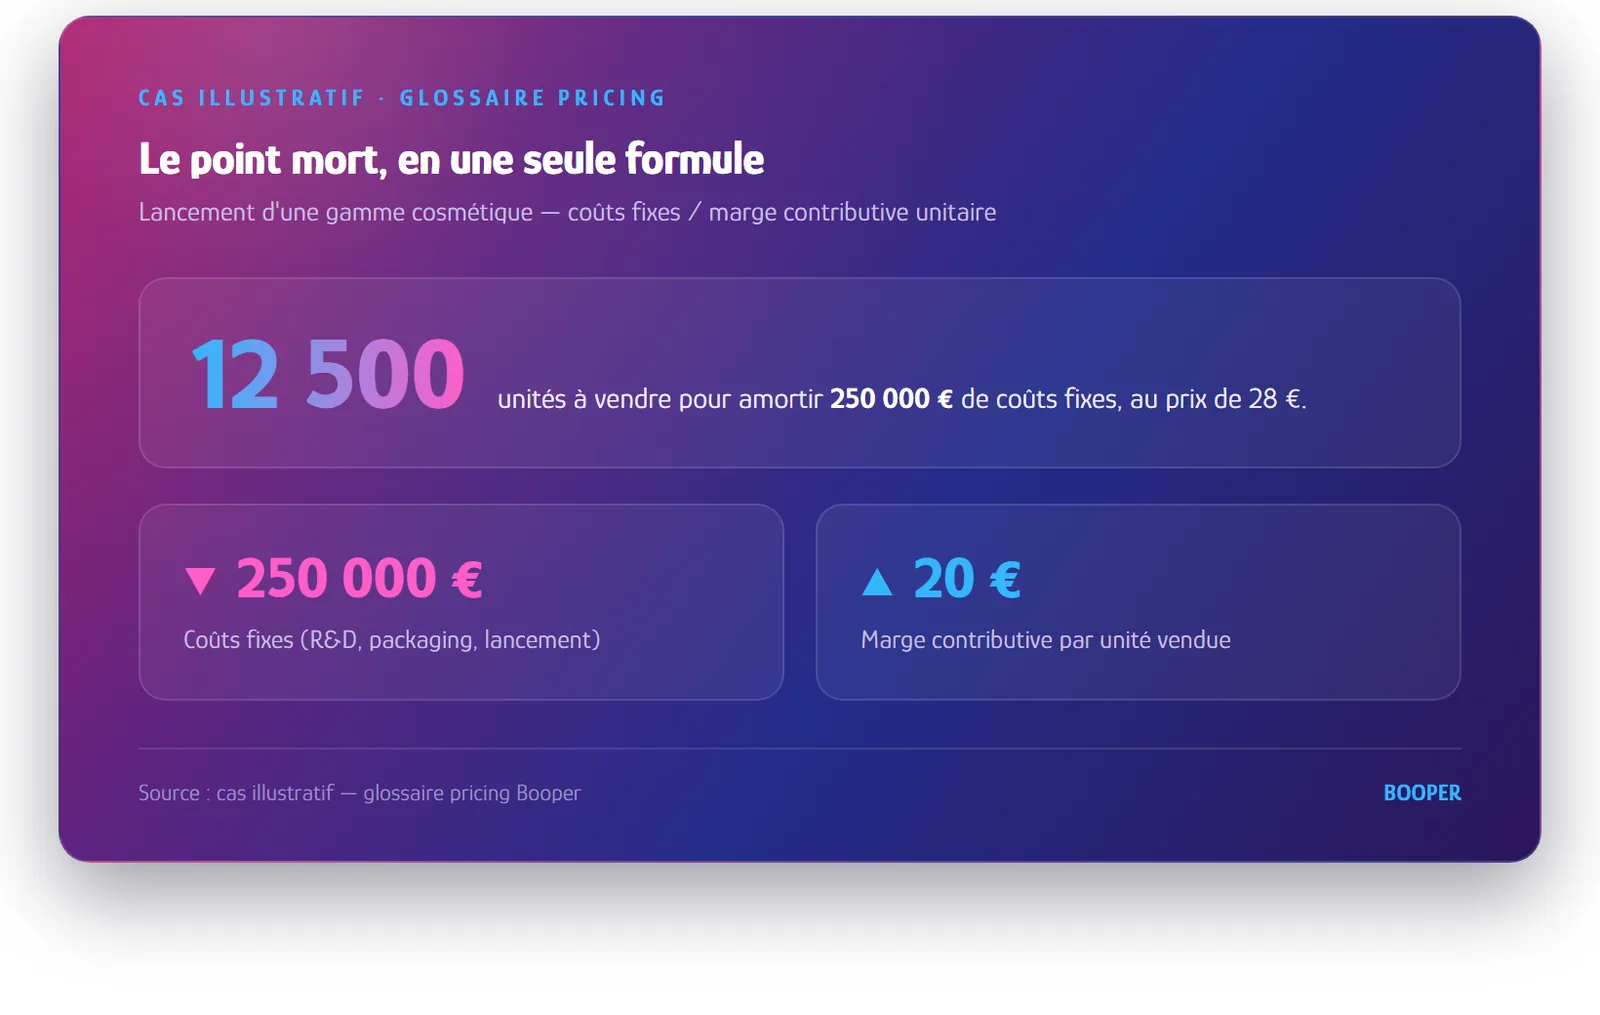
A cosmetics manufacturer is launching a product line with €250,000 in fixed costs (R&D, packaging, marketing) and a variable cost per unit of €8. Sold for €28, each product generates a contribution margin of €20. Beyond 12,500 units, each sale yields a net margin of €20.
How do you calculate the break-even point?
Two formulas—based on volume or revenue—that must be recalculated whenever there is a change in price, cost, or product mix.
| Deadlock | Formula |
|---|---|
| By volume | Fixed Costs ÷ Unit Contribution Margin |
| In terms of revenue | Fixed Costs ÷ Contribution Markup |
Accuracy depends on the distinction between fixed costs (rent, salaries, overhead) and variable costs (materials, per-unit shipping). Our price diagnostic measures the effect of a price change on the break-even point, product by product; our price optimization software simulates this before each decision.
3 Mistakes to Avoid When Using the Neutral Gear
Incorrect reference margin, seasonal factors ignored, and calculations never updated.
- Confusing gross margin with contribution margin: The break-even point is calculated based solely on the margin after variable costs.
- Ignoring seasonality: An annualized break-even point can mask a cumulative deficit that threatens cash flow.
- Do not update: A 12% increase in purchase cost shifts the break-even point by 12% in volume.
The break-even point is one of the key metrics to monitor in pricing, along with margin and price spread.
Frequently Asked Questions
Short answers to the most frequently asked questions about neutral gear.
What is the break-even point?
The break-even point is the sales volume at which a business, product, or project covers all of its costs (fixed and variable) without generating a profit or a loss. Below the break-even point, the business operates at a loss.
What is the difference between the break-even point and the break-even threshold?
The two concepts are related but do not measure the same thing. The break-even point is an amount: the revenue that must be generated to cover all expenses, both fixed and variable. The break-even point is a date: the point at which this threshold is reached, often expressed in days or months after the start of the fiscal year. A business that reaches its break-even point at the end of September has a break-even point of nine months and only makes a profit in the last quarter.
Why is the break-even point important in pricing?
Because it determines whether a pricing decision remains viable. A price reduction lowers the unit margin: to maintain the same profit, it must generate enough additional volume to offset the loss. The break-even calculation provides this volume before the decision is made, not after. Conversely, it helps verify that a price increase won’t cause sales to fall below the level needed to cover costs. It transforms a business intuition into a quantified threshold, open to discussion among the purchasing, pricing, and finance departments.
How can you improve your break-even point?
By leveraging multiple strategies—which should be combined rather than implemented in isolation—such as raising prices when the market allows, improving gross margin (particularly through purchasing terms), reducing fixed costs, or increasing volumes. These strategies interact with one another. A price increase causes volumes to decline, while a price decrease boosts volumes but erodes margins. The best approach is to evaluate these options through simulation, measuring the impact of each scenario on the bottom line before adjusting prices.
Can we calculate a break-even point for each product?
Yes, and it’s often more meaningful than an overall break-even point. It can be calculated by product, category, or project, provided that the associated fixed costs are allocated correctly. This is particularly useful for a product launch—where it indicates the volume needed to recoup the costs incurred—for a promotional campaign, or for a business investment such as a new department. The pitfall to avoid: an arbitrary allocation formula, which makes a product profitable or unprofitable only on paper.
How does the break-even point influence a promotion decision?
It provides the additional volume needed to offset the discount. A price reduction lowers the profit margin per unit: the calculation shows how many more units need to be sold to achieve the same profit. This number is often much higher than what teams anticipate, and sometimes it’s enough to rule out a deal.
Does the break-even point vary depending on the sales channel?
Yes, definitely. The costs of preparation, delivery, and returns for online orders differ from those at the checkout. The same product can be profitable in-store but result in a loss online, even at the same price. Calculating a single break-even point for all channels masks this discrepancy and leads to misguided decisions.
Key Takeaways
- Break-even point = fixed costs ÷ unit contribution margin.
- It determines whether a price cut or a product launch remains profitable.
- It is recalculated whenever there is a change in price, cost, or product mix.
Would you like to know your break-even point before lowering a price?
Booper calculates the impact of a price change on your break-even point, item by item.
Let's talk about your profitability →Discover our price diagnosticThese articles can interest you
Strategic pricing defines, for a period of six to twelve months, the role of each category, the target price level, and the parameters within which daily prices may fluctuate. It does not set prices; rather, it defines the range within which each price is allowed to fluctuate.
A pricing strategy rarely falls apart all at once; rather, it erodes under the weight of accumulated tactical decisions and an ever-growing list of image products. Drawing the line between strategic, tactical, and operational considerations is more important than the sophistication of the calculations.
A calculation yields a price; a simulation shows how that price will affect volume, related SKUs, inventory, and the category’s margin. Automating the calculation isn’t enough: it’s the projection of the effect—scenario by scenario—that influences the decision.
A simulation analyzes price and volume effects—using conservative, balanced, and aggressive scenarios—and then compares the results to actual performance. Its value lies primarily in the fact that it rules out adverse scenarios before they occur in the real world.