
Organic, local, fair trade: the real competitor
67% of French people prefer a local product to a certified organic product when faced with a choice between the two, and about 4 in 10 are "mixers" of organic and conventional products. The price of an organic product should reflect its cumulative perceived value (certification, origin, producer) and not just the fact that it is labeled as organic.
Organic consumers don't just choose between organic and conventional products; they are constantly weighing various claims that partially overlap—organic, local, and fair trade—sometimes all three at once on the same store shelf.
A local product that is not certified organic can thus become a real competitor to an imported organic product. This article explains how this works.

When it comes to making a choice, local beats organic
When consumers are forced to choose between two claims rather than having both appear on the label, their preference clearly leans toward local products.
67% to 33% is the ratio of French consumers' preference for local products (67%) versus certified organic products (33%), primarily for reasons related to food safety and price (Ipsos, April 2025).
This finding does not mean that organic products have lost all their value: it means that the “local” label meets some of the same expectations at a generally more affordable price, without requiring costly certification.
Why Local Food Delivers on Part of the Organic Promise
The association between “local” and “organic” has grown stronger among consumers. Local products are increasingly associated with the absence of pesticides (63%, +6 pts), while the explicit association between “local” and “organic” has declined slightly (60%, -3 pts)—a sign that “local” is establishing its own legitimacy, independent of the label (Ipsos, 2025).
The key factor: proximity and trust in perceived traceability—two expectations that organic products alone do not always meet. A category manager must treat local and organic products as two distinct segments that partially overlap, not as a single market.
The “blender” consumer: the norm rather than the exception
Today, 4 out of 10 French people are “mixers” who alternate between organic and conventional products depending on the item, their current budget, or the purchasing occasion—a behavior that makes price comparisons much more nuanced than a simple binary choice between organic and non-organic (Ifop/So.bio study, April–June 2026).
For this demographic, doubts about authenticity (the second-biggest barrier cited, right after price) carry almost as much weight as the price difference in the decision-making process: a local product with visible traceability can be more reassuring than an imported organic product whose origin remains unclear, even at a comparable price.
Price based on perceived value, not just the label
The price of an organic product should not be based solely on how it compares to its conventional counterpart in the same category. It must also take into account competition from a local, unlabeled product that shares some of the same perceived value, often at a more affordable price.
An organic product that offers no perceptible added value beyond its label (no local sourcing, no identified producer, no emphasis on origin) will lose out to a conventional local product that offers all of these benefits, even at the same price. Conversely, an organic product that combines a label, local origin, and an identified producer can justify a wider price premium without losing perceived competitiveness.
At Booper, GENIUS Predict makes it possible to test the impact of a pricing strategy not only against conventional generic products, but also against identified actual competitors (organic, local, or both) before finalizing a pricing structure. Combined with the analysis from Pricing Optimization Software, this makes it possible to objectively determine which organic products justify a specific price premium.
Frequently Asked Questions
No. A local product that isn't certified organic may appeal to consumers who are looking primarily for perceived value rather than a certification label.
When asked to choose between the two claims, 67% of French people say they prefer a local product to one labeled as organic (33%).
This is a consumer who consciously alternates between organic and conventional products depending on what they are buying. About 4 out of 10 French people identify with this behavior.
By assessing the actual perceived value of each promise (local sourcing, production method, identified producer) rather than setting the price based solely on the label.
See also in this series: Organic Pricing in Retail: The 7 Challenges · Specialty Organic Stores, Supermarkets, and E-commerce: How to Compare Prices · Lowering Organic Prices: Which Products Actually Work.
Further reading
- Perceptions of the Premium for Organic Products: The Real Obstacle Is the Perceived Price Difference
- Data Quality: The Real Glass Ceiling in AI Pricing
- Price Elasticity and AI: Robust Models
- Web scraping, field audits, consumer panels: what are the differences?
- Before deploying a pricing tool, ensure your data is reliable
- Pricing KPIs: Essential Indicators for 2026
- Webinar: Is Your Pricing Predictive or Reactive?
The volume sold during a promotion does not indicate whether it created value: part of it comes from similar products (cannibalization), and another part from purchases that were simply brought forward.
Each promotional scenario must be costed out prior to launch using the same metrics: base sales, actual incremental sales, cannibalization, carryover, halo effect, net margin for the category, and cost per unit actually gained.
Margin-volume arbitrage can then be explained: a stated objective, visible forecasting factors, constraints adhered to, and a documented validation process.
A national food retailer with more than 1,700 stores and several million price points per year: With Booper, its pricing teams simulate the impact of each decision on margins, competitiveness, and price perception before implementing it.
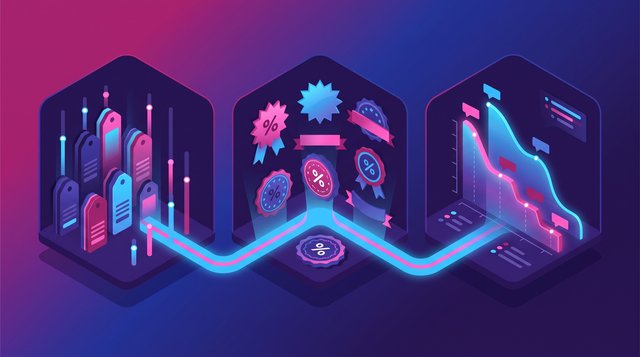
Key takeaway: Pricing, promotions, and markdowns are three factors that constantly influence one another, but are still managed using separate tools at most retailers.
This fragmentation creates inconsistencies that are invisible in the short term (a muddled pricing image, margins eroded by promotions that aren’t properly coordinated with markdowns) but costly in the long term. Gartner has, in fact, formalized this convergence as a distinct market category: unified optimization of pricing, promotions, and markdowns.